
In ten years mobile went from an all-games revenue chart to one led by TikTok, Google One and ChatGPT. In 2016 games held every spot in the global top 15 grossing apps; by 2025 ChatGPT was the most downloaded app in the world (990M) and the #3 grossing app ($1.9B).
Key changes in the top charts
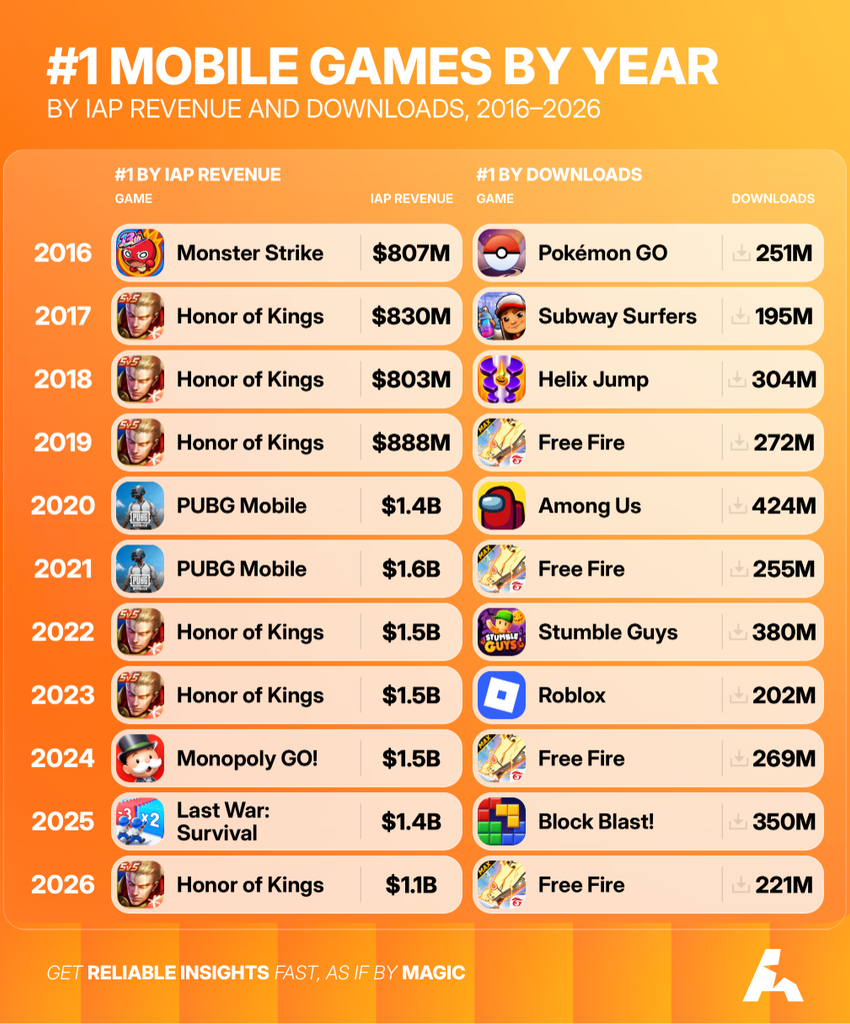
Honor of Kings is the decade’s most durable #1 grossing game, topping the chart in 2017, 2018, 2019, 2022, 2023 and again in 2026.
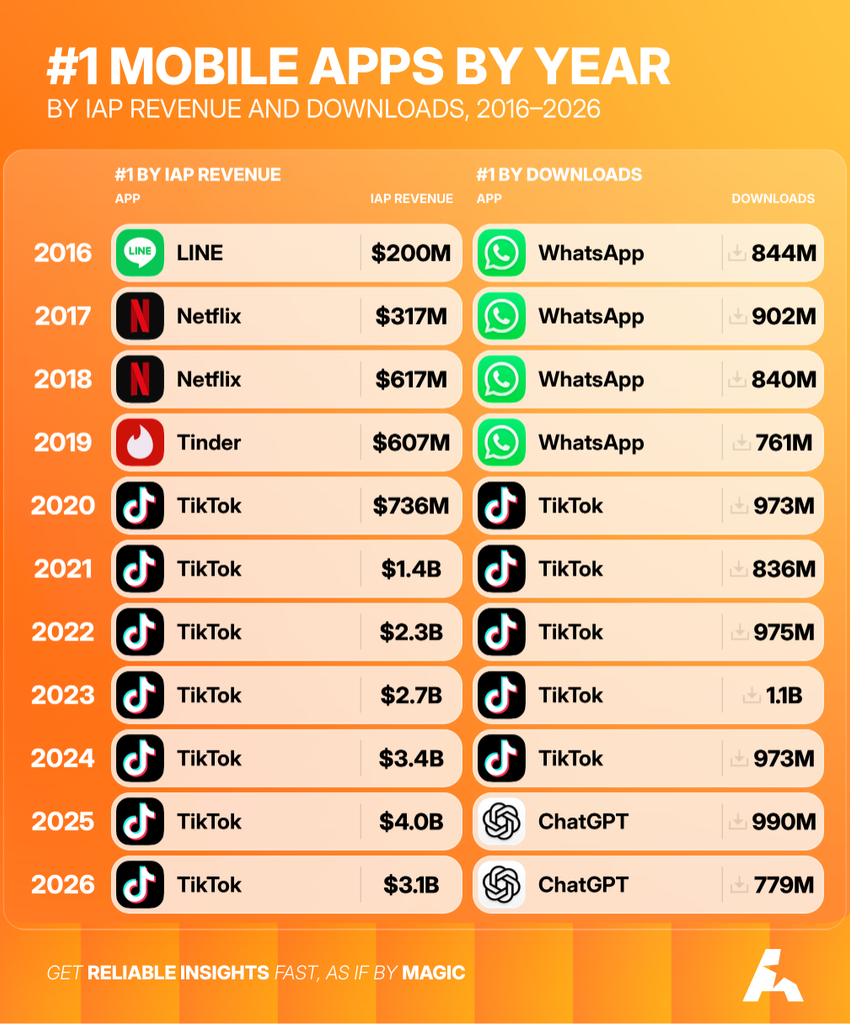
On the apps side, TikTok has been the #1 grossing app every year since 2020. However, Google One and ChatGPT are coming close in 2026 with $2.6B and $2.3B respectively.
Since 2020 TikTok has also been the most downloaded title among both gaming and non-gaming apps, however, its domination came to an end in 2025 with the arrival of ChatGPT.
Main market trends
- Hypercasual’s rise and fall and resurrection. Voodoo’s game Helix Jump led 2018 downloads, and in 2019 Azur Games had four Hypercasual titles in the top 10 free. By 2023 Casual Puzzles like Block Blast! had replaced them. In 2026 trend on Hypercasual, and Arrow Puzzles in particular, followed: Arrows – Puzzle Escape by Miniclip jumped to #5 by downloads (118M) with Amaze GO! by Learnings arriving to #9.
- The pandemic chart. In 2020 apps for online conferences Zoom (698M) and Google Meet (318M) entered the top free apps, and Disney+ revenue rose 720% to $451M. • AI arrives. ChatGPT entered the top 10 free apps in 2024 (336M) and took #1 in 2025. In 2026 the 100 top free apps is filled with AI chatbots, including Chat GPT (#1), Google Gemini (#5), Claude (#15), Meta AI (#26), Grok AI (#42), and others.
- Fast-fashion shopping apps. Temu ranked at #6 free in 2023 with 476M downloads, and SHEIN followed at #10.
- Match-3 changes the leader. Royal Match went from launch in 2021 to #3 grossing game ($1.3B) in 2024, overtaking Candy Crush.
Big acquisitions
Deal sizes grew roughly tenfold over the decade, from King at $5.9B in 2016 to Activision Blizzard at $68.7B and the $55B take-private of EA. Saudi capital became a major buyer, behind both Scopely (2023) and EA (2026).
| Year | Buyer | Target | Value | Why it mattered |
| 2016 | 2016 Activision Blizzard | King | $5.9B | Activision added Candy Crush Saga to its portfolio, and together the two companies reached over 500M users. |
| 2017 | United Luck Consortium | Outfit7 | $1B | United Luck bought Outfit7, the maker of Talking Tom & Friends, then resold it to China’s Zhejiang Jinke. |
| 2018 | Aristocrat | Big Fish Games | $990M | Aristocrat added Big Fish Casino to its portfolio. |
| 2019 | Zynga | Small Giant Games (80%) | $560M | Zynga added Empires & Puzzles, a top-earning Match-3 RPG, to its portfolio. |
| 2020 | Zynga | Peak Games + Rollic (80%) | $1.8B + $168M | Zynga added Toon Blast, Toy Blast and Rollic’s hypercasual games, like Hair Challenge, to its portfolio. |
| 2021 | Microsoft | ZeniMax Media | $7.5B | Microsoft added Fallout, The Elder Scrolls and DOOM to its portfolio. The transaction was designed to secure premium exclusive content for the Xbox ecosystem and the Game Pass service. |
| 2022 | Microsoft | Activision Blizzard | $68.7B | Microsoft added Call of Duty, World of Warcraft and Candy Crush to its portfolio. It was the largest gaming deal to date. |
| 2023 | Savvy Games Group (PIF) | Scopely | $4.9B | Savvy added Scopely and its games, including Monopoly GO!, Marvel Strike Force and Stumble Guys, to its portfolio. |
| 2024 | Playtika | SuperPlay | $700M, up to $1.95B | Playtika added Dice Dreams and Domino Dreams to its portfolio. |
| 2025 | Scopely | Niantic’s games | $3.5B | Scopely added Pokémon GO, Monster Hunter Now and Pikmin Bloom to its portfolio. |
| 2026 | PIF, Silver Lake, Affinity Partners | Electronic Arts | $55B LBO | It was the largest leveraged buyout in history. The deal brought franchises like EA Sports FC, Madden NFL, The Sims and Battlefield under private ownership. |
New important releases
The biggest hits often started small: PUBG Mobile made $99M in its launch year and $9.1B to date, and Free Fire MAX made nothing in 2017 before reaching $3.3B.
| Year | Release | Launch-year revenue | Lifetime revenue | Lifetime downloads |
| 2016 | Pokémon GO | $425M | $5.5B | 716M |
| 2016 2017 | Clash Royale Free Fire MAX | $501M $0 | $3.1B $3.3B | 726M 2.1 B |
| 2017 | Homescapes | $77M | $3.2B | 651M |
| 2018 | PUBG Mobile | $99M | $9.1B | 1.4B |
| 2018 | Brawl Stars | $24M | $2.1B | 555M |
| 2019 | Call of Duty: Mobile RAID: Shadow Legends Genshin Impact | $54M $90M $315M | $1.8B $1.2B $4.1B | 468M 89M 241M |
| 2020 | Among Us | $34M | $52M | 930M |
| 2021 | Royal Match | $144M | $4.7B | 438M |
| 2021 | Umamusume: Pretty Derby | $520M | $1.6B | 19M |
| 2022 | Gossip Harbor | $9M | $1.4B | 158M |
| 2022 | Diablo Immortal | $133M | $371M | 33M |
| 2023 | Monopoly GO! | $731M | $4.5B | 222M |
| 2023 | Whiteout Survival | $225M | $2.9B | 195M |
| 2024 | Pokemon TCG Pocket | $269M | $973M | 145M |
| 2024 | Magic Sort! | $2.4M | $115M | 102M |
| 2025 | Kingshot | $376M | $947M | 114M |
| 2025 | Pixel Flow! | $13M | $137M | 36M |
| 2025 | R.E.P.O (Steam) | $145M | $171M | 22M (copies sold) |
| 2025 | PEAK (Steam) | $91M | $118M | 21M (copies sold) |
| 2026 | Last Asylum: Plague | – | $77M | 26M |
A few contrasts stand out. Among Us reached 930M downloads but only $52M, while Umamusume earned $1.6B from 19M downloads. Gossip Harbor grew from $9M to $1.4B and is one of only three top-10 grossing games still growing in 2026 (+95% YoY for Jan–Oct), alongside Kingshot (+126%) and Honor of Kings (+5%).
In 2025 co-op “friendslop” titles filled Steam’s top 10 premium games by copies sold with tiny indie teams going viral. 4 out of 10 games were “friendslop” that year: R.E.P.O. (18M copies sold), PEAK (16M), Schedule I (9M), and RV There Yet? (6M).
Founded, then famous
Several of today’s biggest hits came from studios founded during this decade.
- 2016, Kolibri Games. The studio became known for Idle Miner Tycoon, which passed 220M lifetime downloads and helped shape the Idle genre.
- 2017, Tripledot. The maker of Solitaire and Woodoku grew into a games group by acquiring AppLovin’s studios (2025) and Supersonic (2026).
- 2017, Trailmix. Known for its Merge game Love & Pies, the studio was majority-acquired by Supercell in 2022.
- 2018, Habby. Its games include Archero, an early Hybridcasual title, and Survivor.io, which later surpassed it.
- 2018, Rollic. Its Hypercasual portfolio includes Hair Challenge, the world’s most downloaded game in May 2021.
- 2019, Dream Games. Its first game, Royal Match, overtook Candy Crush as the top-grossing Match-3 game in 2023 and has earned $4.7B to date.
- 2019, SuperPlay. Famous for its Dice Dreams, SuperPlay was acquired by Playtika in 2024 for up to $1.95B.
- 2020, Metacore. Its hit Merge Mansion was one of the early titles that shaped the Merge-2 market and ranks #3 in the genre by lifetime revenue.
- 2021, Hungry Studio. Its Block Blast! rose from #6 by downloads in 2023 to #1 in 2025. • 2021, Supercent. Its Pizza Ready! was 2025’s most downloaded Hybridcasual game, and Supercent ranked #10 among gaming publishers by downloads that year.
What moved the market in this decade
During this decade two shocks reshaped the business: the 2020 lockdown and Apple’s App Tracking Transparency in 2021.
| Year | Trend 1 | Trend 2 |
| 2016 | Games rule the charts. 2016 was the last year games held every spot in the global top 15 highest-grossing apps. | Pokémon GO. AR gaming went mainstream, and players walked over 8.7B km by year end. |
| 2017 | CryptoKitties. The blockchain cat game clogged the Ethereum network as Bitcoin neared $20,000. | Mobile esports. Clash Royale’s Crown Championship drew 27.4M players. |
| 2018 | Hypercasual. Hypercasual games reached 3.3B downloads, up 84% from 2017. | Fortnite. The game earned $5.48B in 2018. |
| 2019 | Game subscriptions. Apple Arcade and Google Play Pass launched days apart. | Call of Duty: Mobile. Call of Duty: Mobile surpassed 100M downloads in its launch year, making it one of the most successful transitions of a major IP to mobile. |
| 2020 | Lockdown boom. App Store and Google Play spending reached $45.1B, up 24% YoY. | Among Us. It became the most downloaded game of the year, with 424M downloads. |
| 2021 | App Tracking Transparency. Apple’s consent pop-up raised acquisition costs and lowered ad revenue, ressuring Hypercasual. | Pandemic peak. Engagement, spending and investor interest stayed high before the slowdown. |
| 2022 | Post-pandemic slowdown. Player spending fell 6% YoY in Q1, the first decline on record. | Wordle. The daily word game went viral and was bought by The New York Times. |
| 2023 | Royal Match vs Candy Crush. Royal Match overtook Candy Crush as the top-grossing Match-3 game in July. | Shopping apps. Temu entered the top 10 most downloaded apps with 476M downloads. |
| 2024 | Brawl Stars. The game made an epic comeback in 2024, hitting a record $68.1M in monthly IAP revenue in May—over 15 times its 2023 low. | Transmedia. Gaming went transmedia in a big way in 2024: Fallout was a Prime Video smash, Arcane got its second season, and Tomb Raider, Like a Dragon, and Secret Level brought even more game IPs to TV. |
| 2025 | Non-gaming apps. Total IAP revenue of non-gaming apps overtook IAP revenue of all games for the first time ever that year. | AI everywhere. Generative AI took over the app stores with ChatGPT at #1 in downloads and AI assistants everywhere. |
| 2026 | Third-party app stores. Third-party app stores became directly downloadable from Google Play in the US, reshaping store commissions and boosting D2C solutions. | GTA VI. The industry is waiting for its release, scheduled for November 19, 2026. |
Explore the full version of the report on AppMagic website.